One of Britain’s biggest fintech success stories has just made an interesting decision about where to build its international digital asset business.
Revolut, with more than 80 million customers worldwide, has secured a Distributed Ledger Technology (DLT) licence in Gibraltar for its newly established entity, Revolut Global Digital Assets Limited.
The license allows the business to provide regulated digital asset services, including trading, custody and staking.
But why Gibraltar rather than London?
Earlier this year, Revolut was selected to participate in the Financial Conduct Authority’s stablecoin regulatory sandbox, exploring the development of a British pound-backed stablecoin.
At the same time, Revolut publicly raised concerns about aspects of the UK’s proposed stablecoin framework.
In evidence to Parliament, the company questioned restrictions around stablecoin holding limits and requirements for banking groups to separate stablecoin activities under different branding.
Now, just months later, its international digital asset business has received regulatory authorisation in Gibraltar.
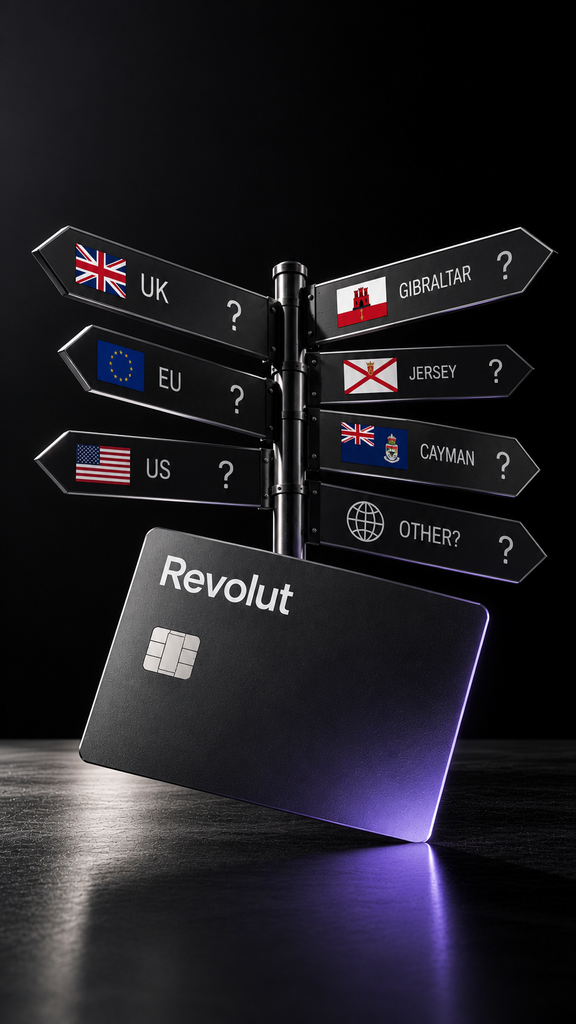
That doesn’t necessarily mean UK regulation caused the decision. Revolut continues to develop its UK and European operations. But it does raise an important question.
Is Britain creating the right environment for the next generation of financial services?
For decades, London has been one of the world’s leading financial centers, attracting capital, talent and innovation. But digital assets are changing the competitive landscape.
Companies developing blockchain infrastructure, stablecoins and digital financial services are no longer limited to traditional financial centres.
Jurisdictions such as Gibraltar, Jersey and the Cayman Islands are increasingly competing to attract these businesses through specialised regulatory frameworks and international financial services expertise.
Of course, regulation is essential. Consumer protection, financial stability and preventing financial crime must remain priorities.
But businesses also need clarity.
Developing financial technology requires significant investment, and companies need to understand the regulatory environment in which their products will operate. If that clarity is available elsewhere, businesses have choices.
The UK is making progress, and its developing crypto asset regime could still provide a strong foundation for innovation.
But the competition is no longer simply between financial institutions. Its between jurisdictions.
Revolut’s Gibraltar expansion is a reminder that the future of finance won’t necessarily be built wherever financial services have traditionally been concentrated.
It will be built where businesses believe they can innovate, operate responsibly and grow.
The technology is moving forward. The question is whether regulation can keep pace.